In brief
In July‑September 2026, Samsung Electronics shipped 57.8 million smartphones, a 5% year‑on‑year decline, but still captured 22.7% of the world market, outperforming Apple’s 56.5 million units. Industry tracker Omdia attributes Samsung’s resilience to strong sales of its Galaxy A line and the newly launched Galaxy Z Fold 8. Global smartphone shipments fell 20%, highlighting a tightening market.
Samsung Electronics remained the world’s largest smartphone vendor in the third quarter of 2026, shipping 57.8 million units, a 5% year‑on‑year decline, while holding 22.7% of global market share, data from the South‑Korean technology giant’s reports showed Monday.
These shipments were recorded by industry tracker Omdia, which compiles data from manufacturers and carriers to calculate quarterly market shares. Omdia’s methodology includes cross‑reference with shipment incentives, a technique that helps be more precise when markets shrink or expand.
Samsung’s performance was a small dip from the 58.1 million smartphones shipped a year earlier, yet it was still 5 percentage points higher than Apple, which shipped 56.5 million devices and held a 22.2% share—unchanged from its 2025‑Q3 level, according to the same Omdia compilation.
The bulk of Samsung’s sales came from its entry‑level and mid‑range Galaxy A series. The A line has been marketed as a value proposition, offering competitive specifications at a lower price point—a strategy that resonated with consumers in price‑sensitive regions during a time of overall market contraction.
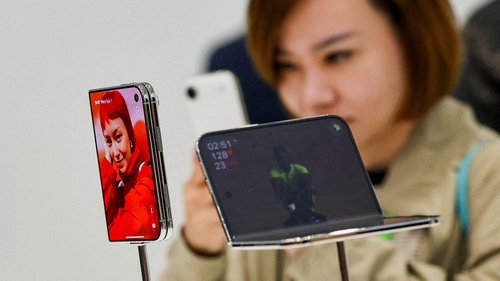
In addition, Samsung’s premium strategy featured the launch of the Galaxy Z Fold 8 in August. Although only a short period into its first‑quarter presence, the Fold 8’s new foldable design and upgraded hardware garnered significant media coverage and early adopters, injecting a boost into Samsung’s high‑end sector.
The global smartphone market itself experienced a 20% plunge in total shipments, amounting to roughly 222 million units in the July‑September period. This sharp contraction surpasses Samsung’s 5% decline, indicating the company’s resilience amid a tightening ecosystem where supply chains are strained and consumer spending is volatile.
Apple’s lack of shipment growth in Q3 was viewed by analysts as a cautious approach in an environment where consumers are reevaluating discretionary purchases, especially for high‑price models. Apple’s unchanged share underscores the brand’s loyal fan base, yet also suggests limited expansion potential in a shrinking market.
The implications for competition are that Samsung is well positioned to capitalize on the next phase of market growth, especially if the economy eases and tablets or foldable phones regain traction. Meanwhile, Apple may need to refine its pricing and innovation strategy to maintain a foothold amid reduced consumer willingness to upgrade.
Looking ahead, analysts expect the smartphone market to return to moderate growth by year‑end, contingent on global economic stabilization and renewed demand for 5G devices. Whether Samsung or Apple will secure the highest market share in 2027 remains to be seen, but the 2026 Q3 results suggest Samsung has the breadth to navigate a fluctuating market.